
3 Testable Mean Reversion Signals for Intermediate Traders

A mean reversion signal flags when price has stretched too far from its statistical average and is likely to snap back. These signals work best on range-bound, low-volatility instruments and fail hard once a market starts trending. The sections below cover the actual indicators, the statistical tests that separate a real edge from noise, and templates you can test this week.
TL;DR:
Mean reversion signals perform best in low-volatility, range-bound conditions, but fail quickly once markets enter trending regimes.
Validating mean reversion requires statistical tests like the Augmented Dickey-Fuller and measuring half-life, not just visual chart patterns.
Combining location indicators (RSI, Bollinger Bands, z-scores) with regime filters (ADX, volatility) improves trade accuracy and avoids false signals in trending markets.
Testing and backtesting strategies with proper statistical validation ensures a stable edge that withstands different market periods and transaction costs.
Automated tools like Big Move Algo incorporate these principles, offering real-time regime filtering and signals across multiple asset classes for practical deployment.
Table of Contents
What Mean Reversion Is and Why It Shows Up in Markets
Prices don’t wander forever. Certain instruments, especially spreads between correlated assets, oscillators built on price extremes, and intraday deviations from VWAP, tend to snap back toward a central tendency after a stretch. The mathematical model behind this is the Ornstein–Uhlenbeck process, which describes a variable pulled toward a long-run mean at a rate proportional to its current distance from that mean. The farther price strays, the stronger the pullback.
You’ll see this behavior show up in a few recognizable places:
Pairs spreads between cointegrated stocks or futures contracts
Oscillator extremes on range-bound indices or forex pairs
Intraday price deviations from VWAP that correct within the same session
Overnight gaps that partially fill during regular trading hours
Mean reversion tends to win in choppy, low-volatility conditions where price has no directional conviction. Trend following does the opposite: it profits from sustained directional moves and gets chopped up in the same sideways conditions where reversion strategies thrive. Knowing which regime you’re in matters more than which indicator you pick.
The Indicators That Actually Generate Reversion Triggers
Most mean reversion strategies combine three layers: a location signal (how far price has stretched), a trigger (the actual entry condition), and a regime gate (confirmation that reversion is even appropriate right now). Skip the third layer and you’ll get chewed up in trending markets.
The core toolkit includes:
RSI(2), popularized for short-term extremes, flags oversold or overbought conditions in as little as two bars
Bollinger Bands (20,2) mark statistical extremes using a 20-period moving average and two standard deviations
Z-score vs. SMA measures how many standard deviations price sits from its moving average, giving a cleaner numeric threshold than visual band touches
VWAP deviation catches intraday stretches from the volume-weighted average, common in equity and futures scalping
Moving-average distance (percentage or ATR-normalized) flags stretch on daily charts
Cointegration and pairs spread z-scores apply the same logic to two correlated instruments instead of one
Timeframe changes everything here. RSI(2) on a 5-minute chart generates dozens of signals a day; on a daily chart, it might fire twice a month. Parameter sensitivity is real: tightening a Bollinger Band from 2 standard deviations to 1.5 will triple your signal count and roughly halve your average edge per trade, since you’re now trading closer to the mean instead of the true extreme.
Pro Tip: Never trade a location signal alone. Pair the indicator extreme with a regime gate, like a flat ADX reading, before you take the trade. A stretched RSI in a strong trend isn’t a signal, it’s a trap.
Testing for Real Mean Reversion: ADF, Half-Life, and Hurst
Eyeballing a chart and seeing “it looks like it reverts” isn’t testing. Before you trust any mean reversion signal, run these checks:
Augmented Dickey-Fuller (ADF) test. This is the standard stationarity test, implemented directly in statsmodels’ adfuller function. A low p-value (typically under 0.05) lets you reject the null hypothesis of a random walk, meaning the series shows statistically meaningful mean-reverting behavior rather than pure noise.
Half-life estimation. Fit an OU-style regression to your series and derive how long it takes price to close half the gap back to its mean. A half-life of 3 days on a strategy with a 10-day holding period is a mismatch; you’re exiting long before the edge plays out, or holding through noise after it’s already gone.
Hurst exponent and autocorrelation. A Hurst value below 0.5 corroborates reversion; above 0.5 suggests trending persistence. Checking lag-1 autocorrelation is a faster, rougher version of the same idea: negative or fast-decaying autocorrelation supports reversion, positive autocorrelation supports momentum.
Backtest hygiene. Build in realistic slippage and commissions, hold out a genuine out-of-sample period, run a walk-forward test across rolling windows, and confirm your best parameters aren’t wildly different from neighboring ones. A strategy that only works at RSI period 2 but collapses at period 3 is fitted noise, not a signal.
A workable edge needs both speed and stability: the half-life has to be short relative to your transaction costs, and the statistics need to hold up across multiple subperiods, not just one lucky year, as practitioner research on regime dependence points out.
Strategy Templates You Can Build and Test This Week
Here are three concrete templates, not abstract theory, that map directly to the indicators and tests above.
Bollinger + RSI(2) intraday template. Enter long when price closes below the lower Bollinger Band (20,2) and RSI(2) reads under 10. Place your stop 1.5x ATR below entry. Target the middle band (the 20-period SMA) or exit on a time stop after 8 to 10 bars if the mean hasn’t been touched. This setup suits liquid index ETFs and large-cap stocks on 5 to 15-minute charts.
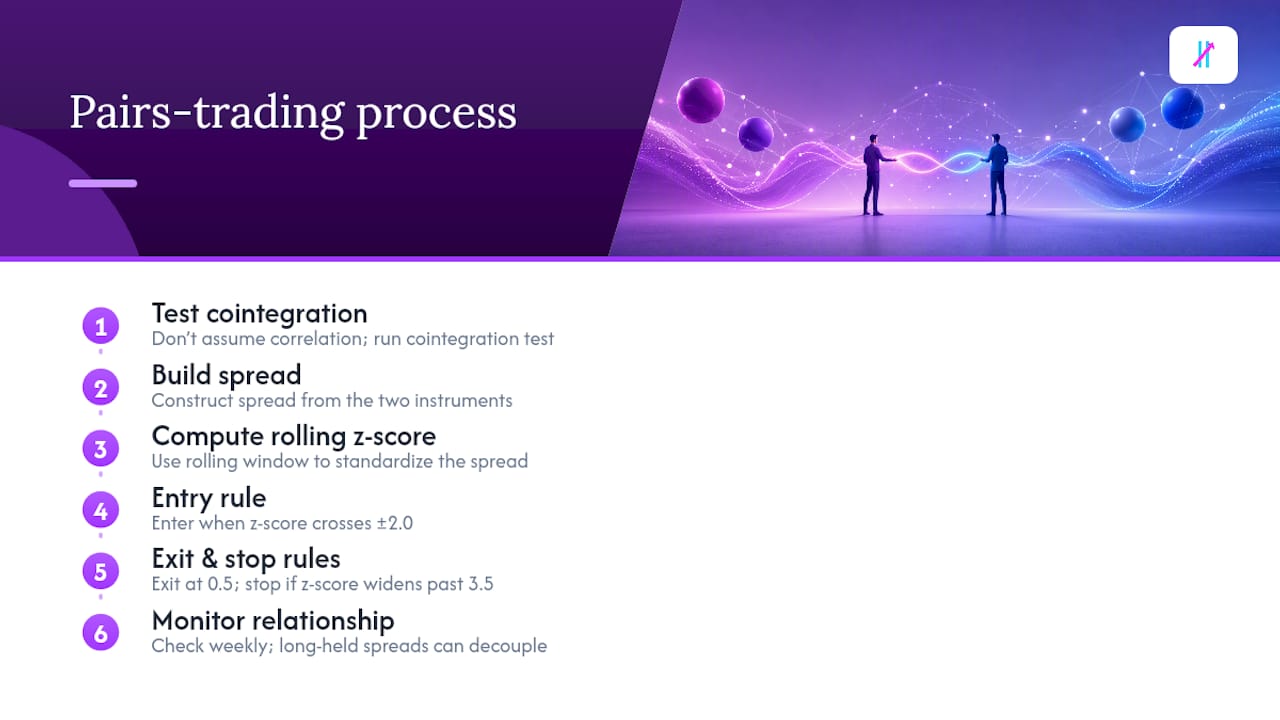
Pairs trading blueprint. Build a spread from two cointegrated instruments (test cointegration first, don’t assume correlation implies it). Compute a rolling z-score of the spread. Enter when the z-score crosses 2.0 in either direction, betting the spread reverts to zero. Exit at a z-score of 0.5 or on a stop if the z-score keeps widening past 3.5, which usually signals the cointegration relationship has broken down. Monitor the relationship weekly; spreads that held for two years can decouple permanently.
Volatility-aware exits. Use time-based exits in choppy, low-momentum conditions where price may never cleanly touch your target, and target-based exits when volatility is elevated and moves happen fast. Cap yourself at 3 to 5 simultaneous open trades and set a daily loss limit around 2% of account equity across all positions combined.
Position sizing example. Risk 0.5% to 1% of account equity per trade, with position size calculated as risk amount divided by (ATR stop distance × dollar value per point). If your average win is 1.2x your average loss and you win 58% of trades, your expectancy per trade is (0.58 × 1.2) minus (0.42 × 1), or roughly 0.28R, a real edge, but one that evaporates fast if slippage eats even a third of it.
Pro Tip: Calculate expectancy in R multiples, not dollars, before you ever size a position. A strategy with a 45% win rate and a 2.5:1 reward-to-risk ratio beats a 65% win rate strategy with a 1:1 ratio, even though the second one “feels” better.
When to Turn Mean Reversion Off
Mean reversion strategies lose money fastest in trending regimes, so the regime filter matters as much as the entry signal itself.
ADX above 25 to 30 on your trading timeframe generally signals a developing trend; treat reversion signals as unreliable above that threshold
ATR running well above its 20-period average signals expanding volatility, often the front edge of a trend, not a range
Higher-timeframe moving-average slope (check the 50 or 200-period MA on a daily chart even if you trade intraday) tells you the dominant direction you’re fighting
Hard stops and time stops together, not one or the other, since a stretched position that isn’t reverting on schedule is telling you something
Daily loss caps and a max simultaneous trade count prevent one bad regime shift from compounding across a full basket of correlated positions
Reduced sizing or a hybrid split between a reversion sleeve and a trend sleeve smooths the equity curve when you can’t be certain which regime you’re in
Implementation Notes From Big Move Algo
Big Move Algo runs as a TradingView indicator delivering real-time Long, Short, and Exit signals. AUTO mode requires minimal setup; Manual mode adds customization for experienced traders. The built-in Fake Trend Detector functions as a practical regime filter, flagging low-quality conditions before you trade them. See our guide on trend versus reversion regime checks for implementation detail.
When Mean Reversion Belongs in Your Mix
Mean reversion rewards traders with short holding periods, low-cost execution, and access to liquid instruments where spreads don’t eat the edge. If you can’t test rigorously or trade cheaply, a trend or hybrid approach carries less emotional cost, since reversion strategies post frequent small wins punctuated by occasional sharp, uncomfortable losses.
— Steven Hartwell
Putting Signals to Work Without the Manual Overhead
Running ADF tests and half-life calculations before every trade is the right discipline, but most traders don’t want to rebuild that pipeline for live execution. Big Move Algo is built for exactly that gap: it takes the regime-gate logic this guide covers, ADX-style trend detection, volatility checks, location extremes, and turns it into a real-time Long, Short, or Exit signal on your TradingView chart.
The Fake Trend Detector filters out the low-quality, choppy-but-not-quite-ranging conditions that wreck untested reversion entries, and AUTO mode gets you running with minimal configuration while Manual mode stays open for traders who want to tune thresholds themselves. It runs across crypto, forex, stocks, indices, and commodities, with alerts that can feed into automated execution platforms. If you’re connecting an existing account, the TradingView setup guide walks through the process. Subscription plans are available for different versions; see the pricing page for current details. Head to Big Move Algo to see current plan options and get instant access.
Sources
To run the tests covered above yourself: statsmodels’ adfuller function handles stationarity testing, NumPy and pandas supply the array math and rolling-window tools for z-scores and VWAP, and the Ornstein–Uhlenbeck process page grounds the half-life math theoretically. If you’re trading tokenized equities or crypto-adjacent instruments, the regulatory landscape is shifting fast; see this analysis of the SEC’s tokenized stock exemption for context on how that market structure is evolving.
FAQ
What Are the Best Indicators for Mean Reversion Trading?
RSI(2), Bollinger Bands (20,2), z-score of price versus its moving average, and VWAP deviation are the most widely used mean reversion indicators. Pairs traders add cointegration testing and rolling spread z-scores. The strongest setups combine a location signal with a regime filter, like ADX, rather than trading the indicator alone.
What Is the 3-5-7 Rule in Trading?
It’s a general risk-management framework, not specific to mean reversion, but it pairs well with the daily loss caps covered above.
What Are the Big 3 Indicators in Trading?
There’s no single official “big 3,” but moving averages, RSI, and Bollinger Bands are the three most commonly cited indicators across both trend and mean reversion strategies. For reversion specifically, Bollinger Bands and RSI(2) do most of the heavy lifting, with moving-average distance serving as a supporting confirmation.
What Is an Example of Mean Reversion?
A stock trading 2.5 standard deviations below its 20-day moving average, with RSI(2) under 5, is a classic mean reversion setup: statistically stretched, likely to snap back toward its average absent a trend change. Pairs spreads that widen past a 2.0 z-score before narrowing back toward zero are another common real-world example.
Does Big Move Algo Work for Mean Reversion Setups?
Big Move Algo generates real-time Long, Short, and Exit signals with a built-in Fake Trend Detector that filters out low-quality, non-ranging conditions, functioning as a practical regime gate for reversion-style entries. It runs on TradingView across crypto, forex, stocks, indices, and commodities, with AUTO mode for fast setup and Manual mode for custom thresholds.
Recommended
Comments